Let’s be honest. Wrapping up a Medicare Advantage application feels great. But then comes the tricky part. You mention cross-selling hospital indemnity or a cancer policy, and your client instantly puts their guard up. “No thanks, I’m good.”
Sound familiar?
It happens to all of us. Nobody wants to act like a pushy salesman. And your clients are usually tired of looking at paperwork by that point anyway. So, how do you get them to actually see the value without being annoying?
Stop handing out brochures. Start telling stories.
Make the Risk Feel Real
Let me give you an example. Meet Bob. Bob is a past client who loved his zero-premium MA plan. But last year, Bob ended up in the hospital for five days. Suddenly, he was staring down a $350 daily copay. That hurts.
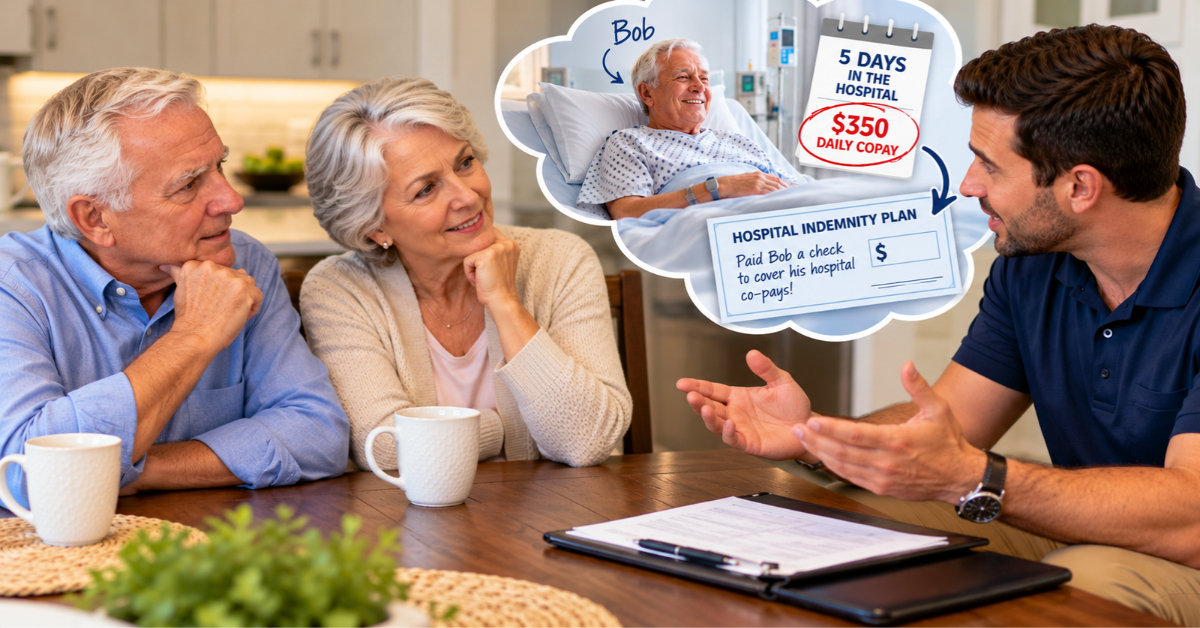
When you share a real story like Bob’s, the risk stops being just abstract numbers on a page. Tell your client how a simple Hospital Indemnity policy actually handed Bob a check to pay those exact bills. You aren’t pitching a product anymore. You are just a friendly neighbor giving a heads-up.
This works wonders for cancer plans, too. Tell them about a family who got a lump-sum cash payout right after a scary diagnosis. That money bought them peace of mind when they needed it most. With the cost of cancer treatments being so expensive, this is one specific area that a Medicare Advantage client could actually hit their maximum out of pocket (MOOP) twice in a 12 month period of time. Wondering how that could happen?
There is no specific time of year that folks get diagnosed with cancer. Let’s say your client is diagnosed with cancer in the month of June and begins treatment in July. Additionally the treatment lasts for only 10 months. What happens to your client who has a Medicare Advantage plan that has a 20% co-insurance payment for cancer treatments?
Well if their share is only running around $800 per month, then they will have an out of pocket cost of $4,800 during the first 6 months and since they would be continuing treatment into the beginning of the next year, they will start a new MOOP. The remaining 4 months would cost them an additional $3,200. This means that in a 10 month period (split between 2 calendar years) they would be out $8,000 for just the cancer treatment costs.
Where does that money come from? Usually from their retirement plan or savings. Since they are retired, there is no additional income coming in to replace that money. This can cause hardships down the road.
Instead you can alleviate this risk with a cancer plan. A 70 year old can get a $10,000 cancer plan for around $30 per month or $1 per day.
Partner with a Team that Has Your Back
Getting the conversation right is a huge piece of the puzzle. But you also need decent products and a reliable crew behind you to actually get the business placed. That is where we step in.
Here at Senior Benefit Services, we hook independent brokers up with exactly what you need to win in this market:
-
Top-Tier Carrier Portfolio: We give you access to the absolute best carriers for Hospital Indemnity and Cancer/Heart Attack/Stroke plans. We even have options with those popular Return of Premium riders. These pair up perfectly with Medicare Advantage, filling those dangerous coverage gaps while boosting your revenue on every single appointment.
-
Specialized Back-Office Support: Forget about guessing on underwriting. Our back office is loaded with senior market veterans. We help you figure out those messy health profiles so you can find the exact right fit for your client.
-
Agent-Focused Training: We do a lot of ongoing coaching. Need more tips on story-selling? We have you covered. We want you keeping clients on the books longer and feeling great about the coverage you sell.
When you match a real story with a solid product, making that extra sale doesn’t feel like a chore. It just feels like doing right by your people.
Contact our team today to learn how to add these products to your portfolio.